Buyer's Guide · Updated October 2026

The Fort Lauderdale Luxury Buyer's Guide

Waterfront homes and condos from $2M, explained by someone who lives here.
Updated October 2026 · 12-minute read

Four things the listing photos don't show

In Fort Lauderdale, the house is usually the easy part. Buyers at $2 million and up win or lose on four things the listing photos don't show: the water route from the dock to the ocean, the seawall, the insurance, and (in a condo) the building's balance sheet.

This guide covers each of them in plain English, with the Broward-specific rules and costs. You'll be able to tell a great waterfront home from one that only photographs well, and you'll know what to ask before you sign anything.

The quick answer: how to buy a luxury home in Fort Lauderdale
  1. Decide how you'll live here: full-time or seasonal, single-family or condo, boat or no boat.
  2. Get your financing settled. At these prices that usually means a jumbo loan, a portfolio loan or cash.
  3. Match the vessel to the address (bridge clearances, depth and dock size) before you fall for a house.
  4. Price the insurance and flood exposure before you make an offer, not after.
  5. Inspect the seawall and dock separately from the house. For condos, read the building's reserve study and inspection reports.
  6. Budget the Broward closing costs and the property-tax reset that follows a purchase.
  7. If this will be your primary home, plan your Florida domicile and homestead filing.

Want the short version for your search?

Book a 20-minute buyer consultation. We'll talk through your budget, your neighborhoods and your boat, and you'll leave with a written plan.

Book My Buyer Consultation
Chapter 1

Let the water choose the neighborhood

Before you choose a house, your boat chooses the canal. Two homes on the same street can have a very different run to the ocean.

Dock-Fit: measure the boat before you measure the closets

I start every waterfront search with four numbers, for the boat you own now and the boat you'll own in five years. We buy for the second one.

  • Length and beam: set the dock length, canal width and turning room you need.
  • Draft: compare it to documented depth at the dock at mean low water, not at high tide.
  • Air draft: the height to your highest fixed point. It decides which bridges you clear without an opening.
  • Lift: check capacity, permits and condition.

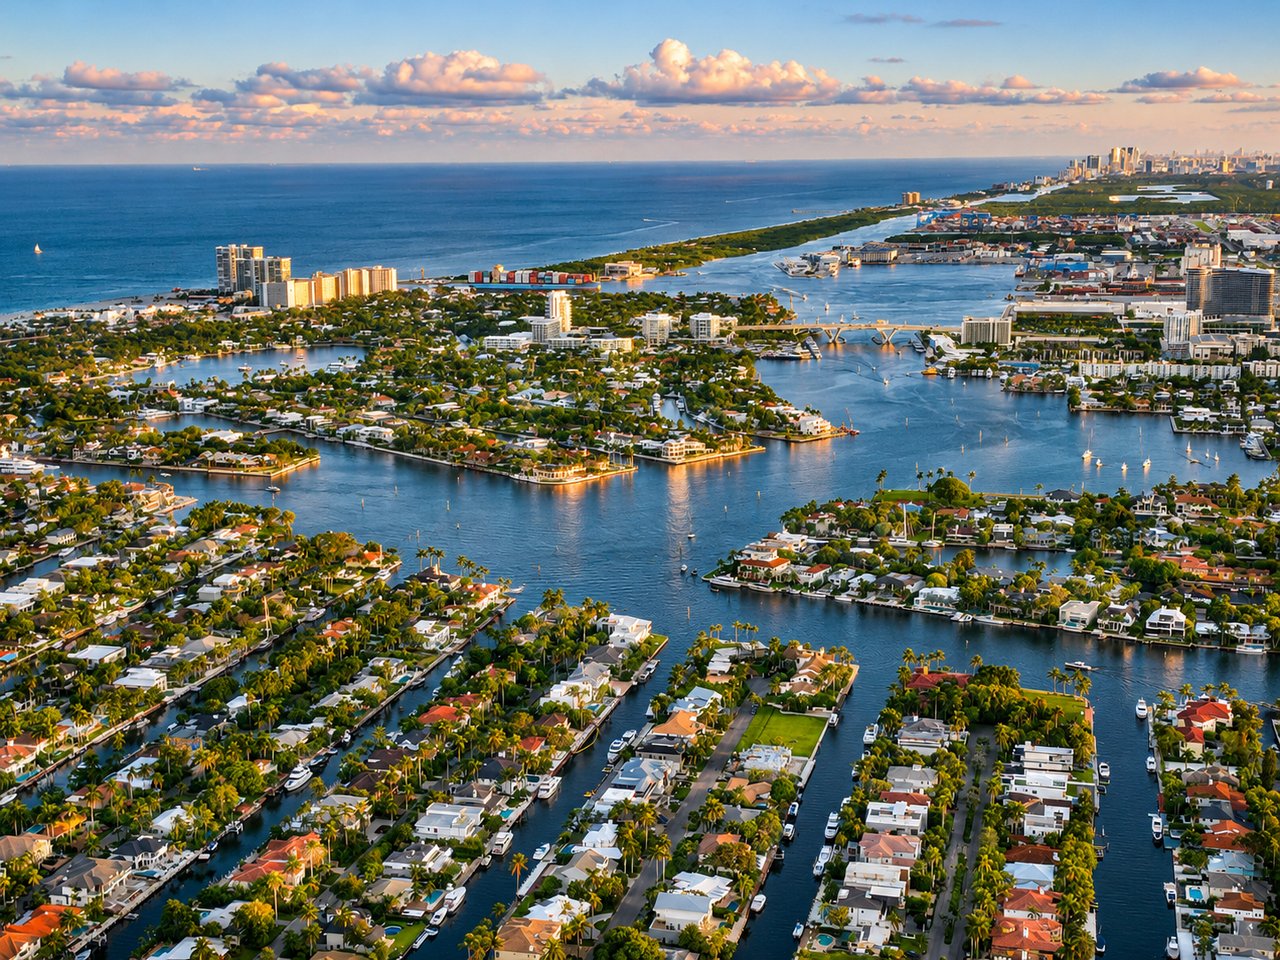
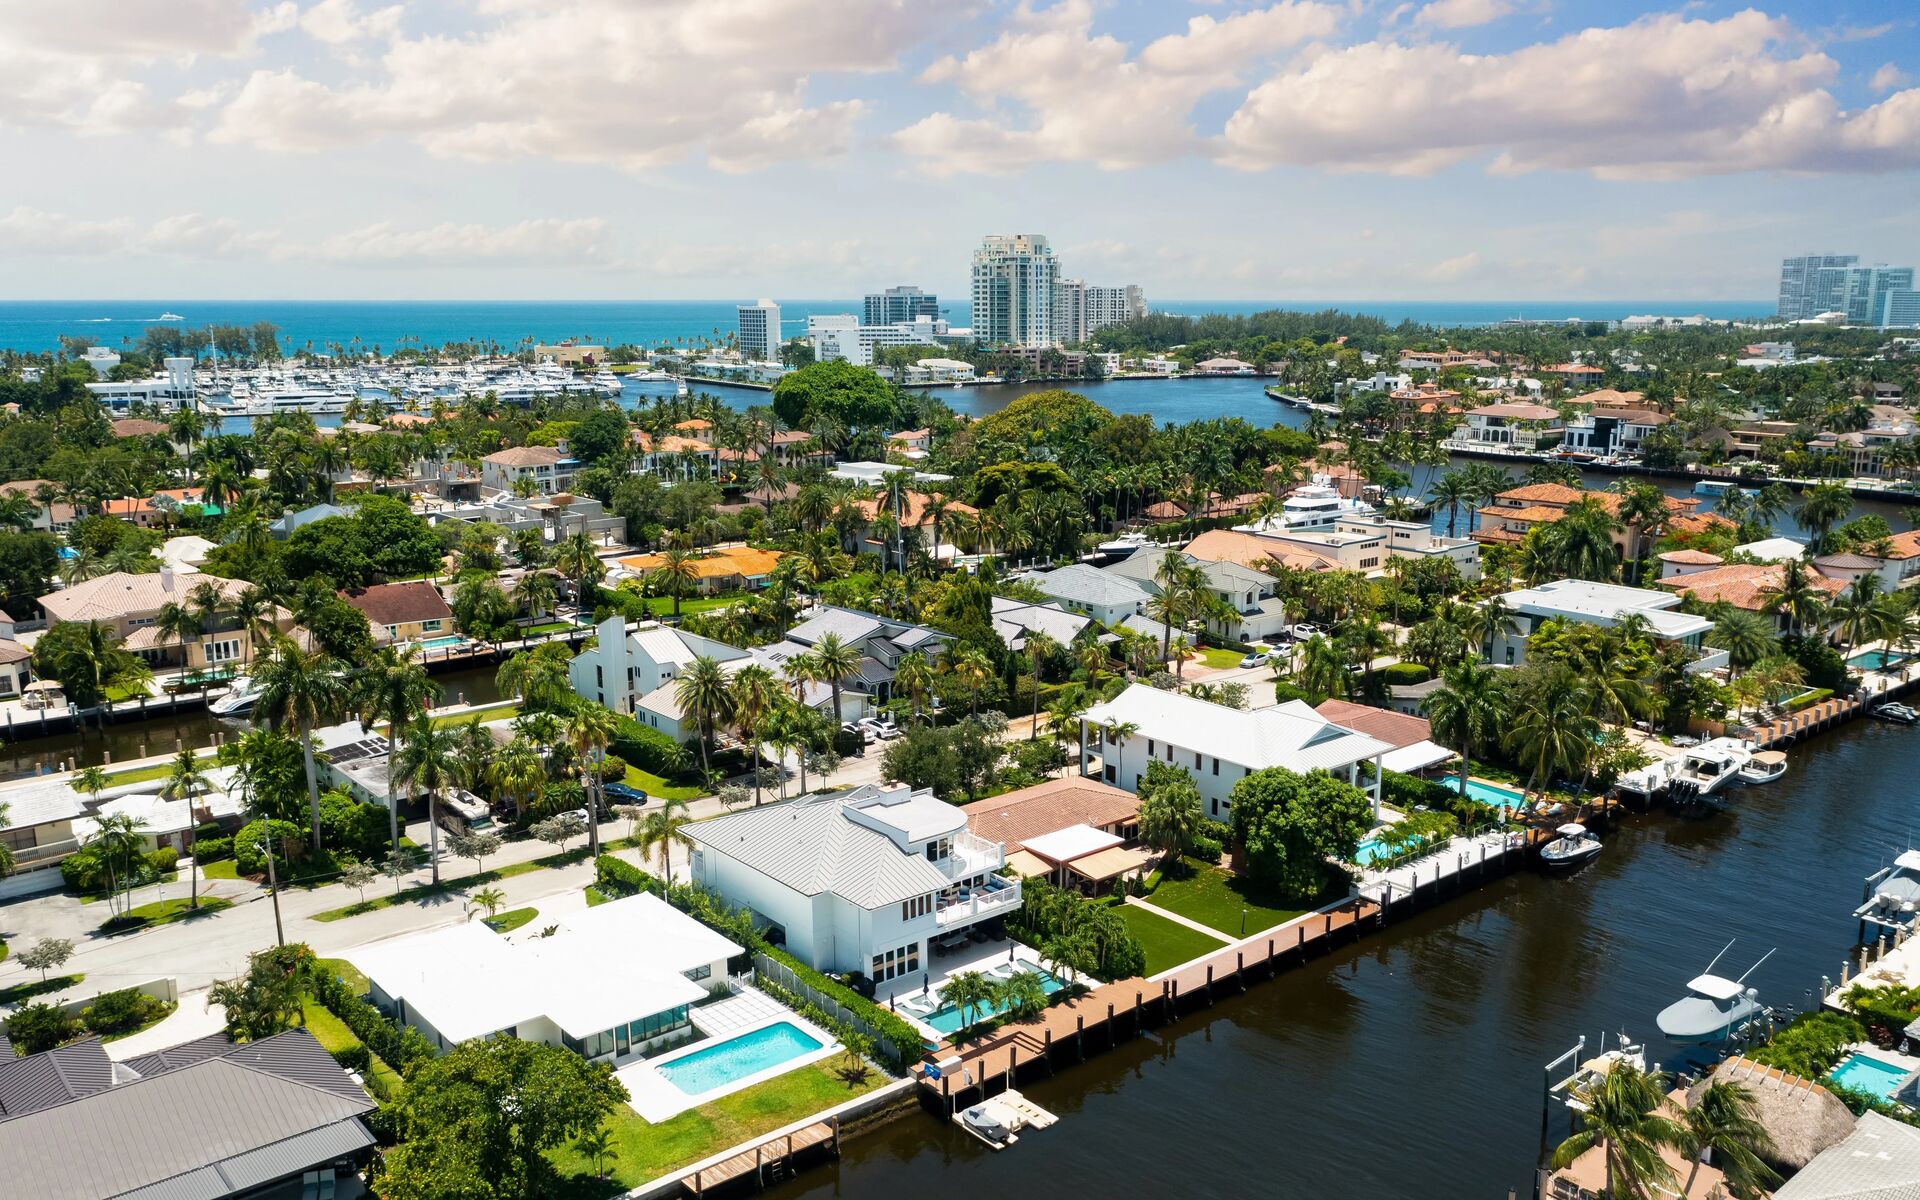
Aerial view of the Intracoastal Waterway and the 17th Street Causeway bridge in Fort Lauderdale

The bridges between you and the Atlantic

Most Fort Lauderdale boaters reach the ocean through Port Everglades. The key Intracoastal bridges are drawbridges that open on a schedule. Closed clearances at mean high water:

Bridge (Intracoastal)

Closed clearance

Openings

East Sunrise Boulevard

25 ft

On the hour and half hour

East Las Olas Boulevard

31 ft

Quarter past and quarter to the hour

SE 17th Street Causeway

55 ft

On the hour and half hour, with weekday rush-hour limits

Source: U.S. Coast Guard drawbridge regulations. Schedules change and bridges close for repairs.

"No fixed bridges" means a tall boat can always get out. It doesn't mean you'll never wait. Which bridges a dock passes depends on where it sits relative to Las Olas Boulevard and the 17th Street Causeway, so I map the route address by address.

Dock rules matter too. In Fort Lauderdale, a dock or lift generally can't extend more than 25% of the waterway's width or 25 feet past the property line, whichever is less (ULDR §47-19.3). A narrow canal can cap the boat you're able to keep.

Tell me the boat and I'll tell you the streets.

Set up a private search filtered by vessel size, bridge clearance and neighborhood. You'll get matches I've checked, not a portal feed.

Set Up My Private Search
Chapter 2

The neighborhood decoder

Every neighborhood below has its own page with live listings. This is the short version I give buyers on day one.

Neighborhood

What it's known for

Who it tends to suit

Las Olas Isles

Finger isles off Las Olas Boulevard, deep-water estates, walk to dinner

Boaters who want the boulevard on foot and the ocean by water

Harbor Beach

Waterfront estates near Port Everglades, with a short run to the inlet

Larger-yacht owners for whom inlet time matters most

Rio Vista

Mature canopy, river and canal lots, minutes to downtown

Buyers who want old-Florida streets close to the city

Coral Ridge

Intracoastal and interior canal homes north of Sunrise Boulevard, with a wide range of lot sizes

Buyers who want waterfront space and a residential feel

Colee Hammock

Historic streets along the New River, steps from Las Olas

Buyers who want character and walkability

Victoria Park

Mostly non-waterfront luxury, new construction and townhomes near downtown

Buyers who want to be close to Las Olas without a waterfront price

Lauderdale Beach and the beach corridor

Oceanfront and ocean-view condos, branded residences

Lock-and-leave owners and seasonal residents

Sunny Isles Beach and Golden Beach

Miami-Dade: oceanfront towers (Sunny Isles) and estate homes (Golden Beach)

Buyers comparing Broward with northern Miami-Dade


Browse all of them on the neighborhoods page, or read my street-level posts on the blog.

Chapter 3

Financing a $2M+ purchase

Jumbo, portfolio or cash

For 2026, the conforming loan limit in Broward County is $832,750 for a single-family home. Any loan above that is a jumbo loan, so nearly every financed purchase in this guide is jumbo. FHFA announces the 2027 limits in late November.

What changes at this level:

  • Underwriting is lender-specific. Down payment, cash reserves and debt-to-income limits vary. Compare two jumbo lenders and a private bank.
  • Asset-based and portfolio loans can qualify you on assets rather than income. They suit business owners and retirees.
  • Cash is common. In July 2026, 34.5% of all Broward closed sales were cash (Florida Realtors data). Some buyers pay cash to win on terms and finance afterward; confirm that path with your lender first.
  • Insurance is part of the loan. Lenders won't fund until coverage is bound, and Florida insurers stop writing new policies during a hurricane or tropical storm watch or warning. Bind early in storm season.
Insurance is part of the loan.

Condo loans changed in 2026

Since August 3, 2026, most conventional condo loans require a Full Review of the building's finances: budget, reserves, special assessments and engineering reports. For applications dated on or after January 4, 2027, Fannie Mae requires the building's budget to put at least 15% of assessment income into reserves, up from 10%. A building with unresolved critical repairs isn't eligible. I explain what this means for Las Olas buyers in Your Las Olas condo loan now depends on the building's balance sheet.

I started my career in mortgages, so I read a lender's checklist before I read the listing.

Chapter 4

Waterfront due diligence: five checks that protect the price

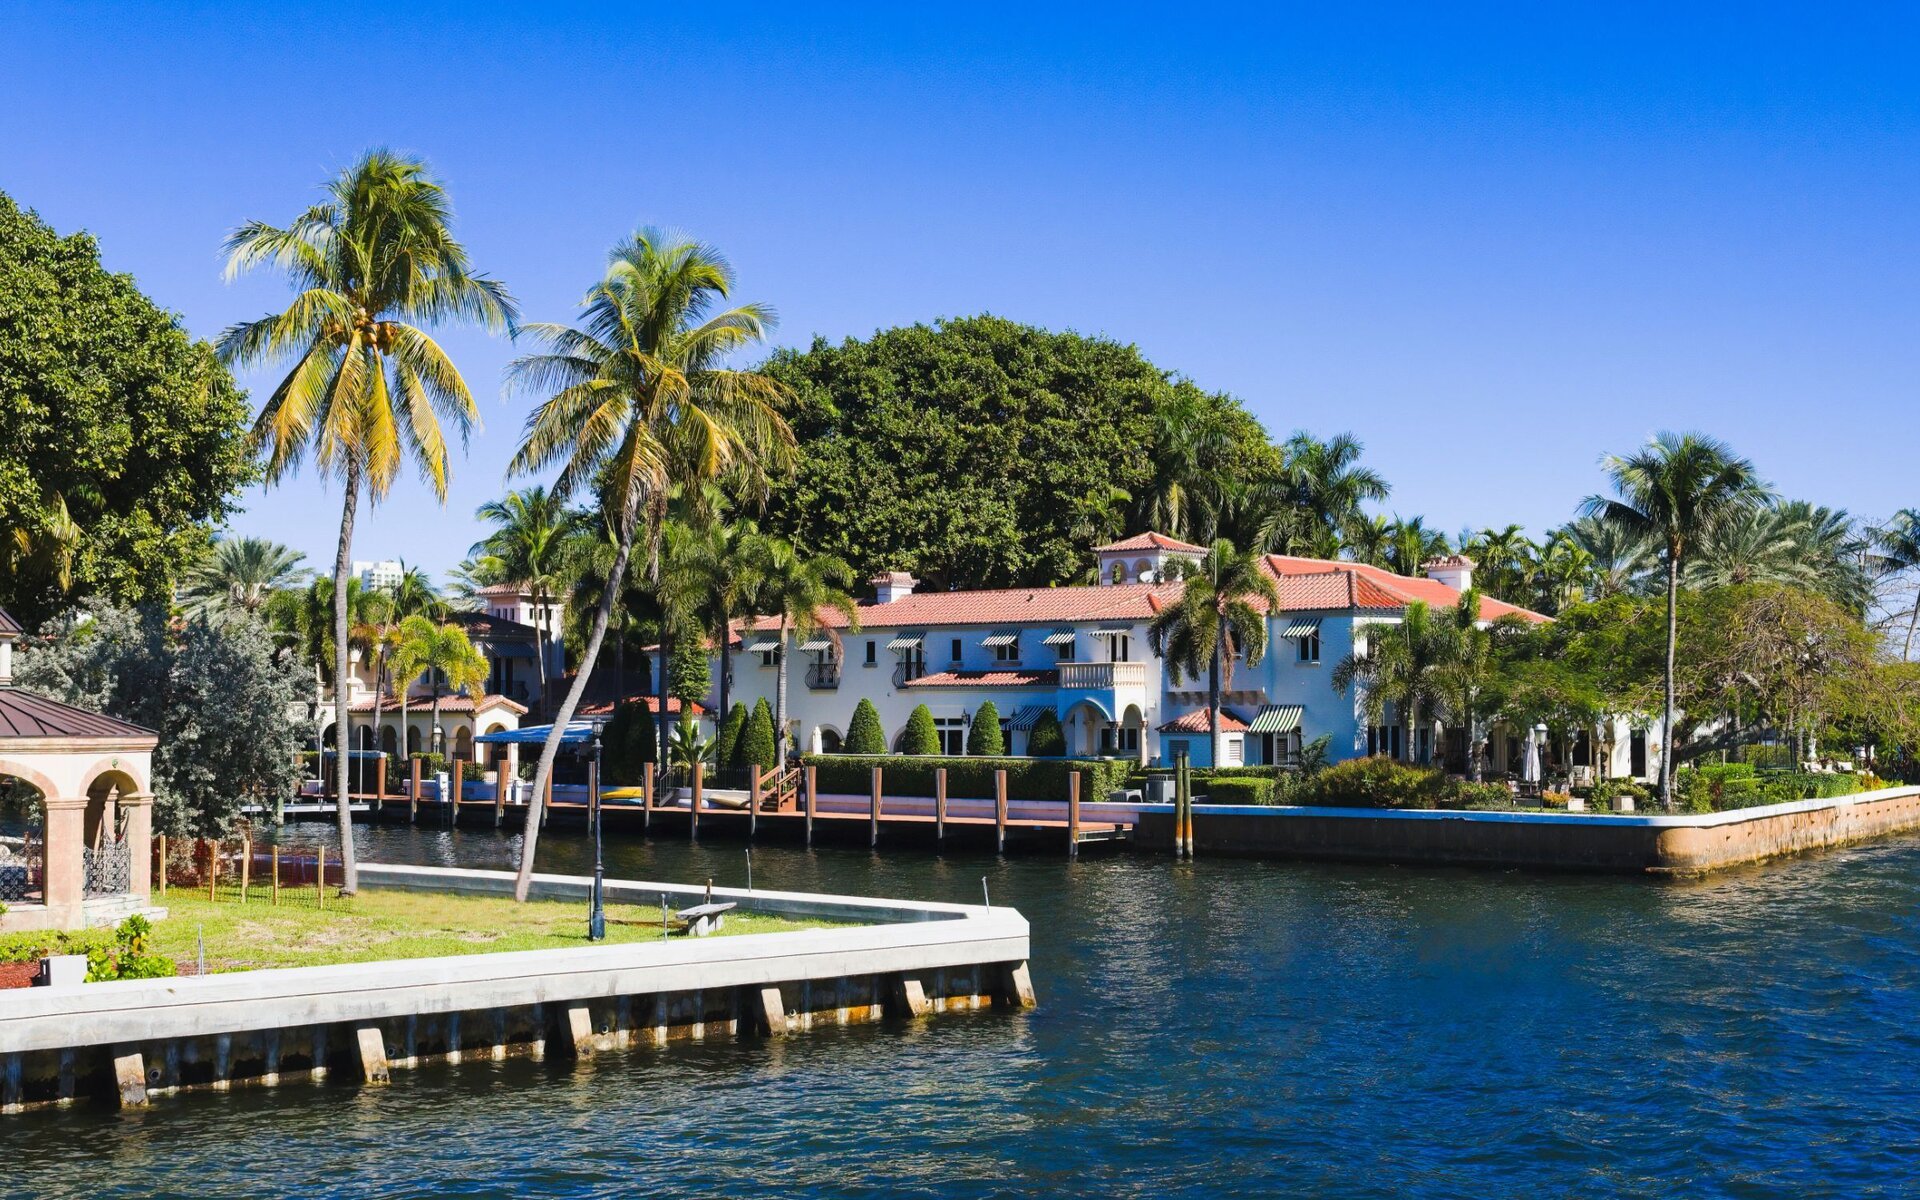
Close-up of a seawall and private dock on a Fort Lauderdale canal

The seawall is part of the price

Fort Lauderdale requires new or substantially repaired seawalls to reach 5.0 feet NAVD88. Permits applied for before January 1, 2035 can build to 4.0 feet if the wall is designed to reach 5.0 feet by 2050 (ULDR §47-19.13). A big "repair" can become a rebuild.

A general home inspection doesn't cover seawalls. Hire a licensed marine contractor or engineer, and pull the permit history for the wall and the dock. More detail: The seawall rule Las Olas Isles buyers and sellers already live under.

Survey, permits and title

Order a current survey showing the seawall, dock and any encroachments, and have the title agent search for open permits and municipal liens.

The dock itself

Confirm the dock's permit, condition and power, and whether the slip is deeded, assigned or shared. In condos, that matters most: the Las Olas Marina has 88 slips, and your waterfront condo might not have one.

Flood zone, elevation and the 50% rule

  • Check the flood zone on the City of Fort Lauderdale's flood-zone map and ask for the elevation certificate. AE zones are high risk; VE zones add wave hazard.
  • Planning a big renovation? Under the 50% rule, if improvements in a flood zone reach 50% of the building's market value, the home must meet current flood rules, which can mean elevating it. The city counts work over a rolling two-year period.
  • Since October 1, 2025, sellers must give a written flood disclosure at or before contract (§689.302, F.S.), covering known flood damage, claims and assistance.

Insurance before you fall in love

Get wind and flood quotes before you make an offer.

  • NFIP flood policies top out at $250,000 for the building, so luxury homes usually add private excess flood.
  • From January 1, 2027, Citizens requires flood coverage on every residential policy with wind, in any flood zone. Condo unit-owner policies are exempt.
  • A wind-mitigation inspection can lower your premium. Order one during the inspection period.

Want my due-diligence checklist for a specific home?

I'll walk it with you, and with the marine contractor if you'd like, before your inspection period ends.

Book My Buyer Consultation
Chapter 5

Condo or single-family at $2M and up?

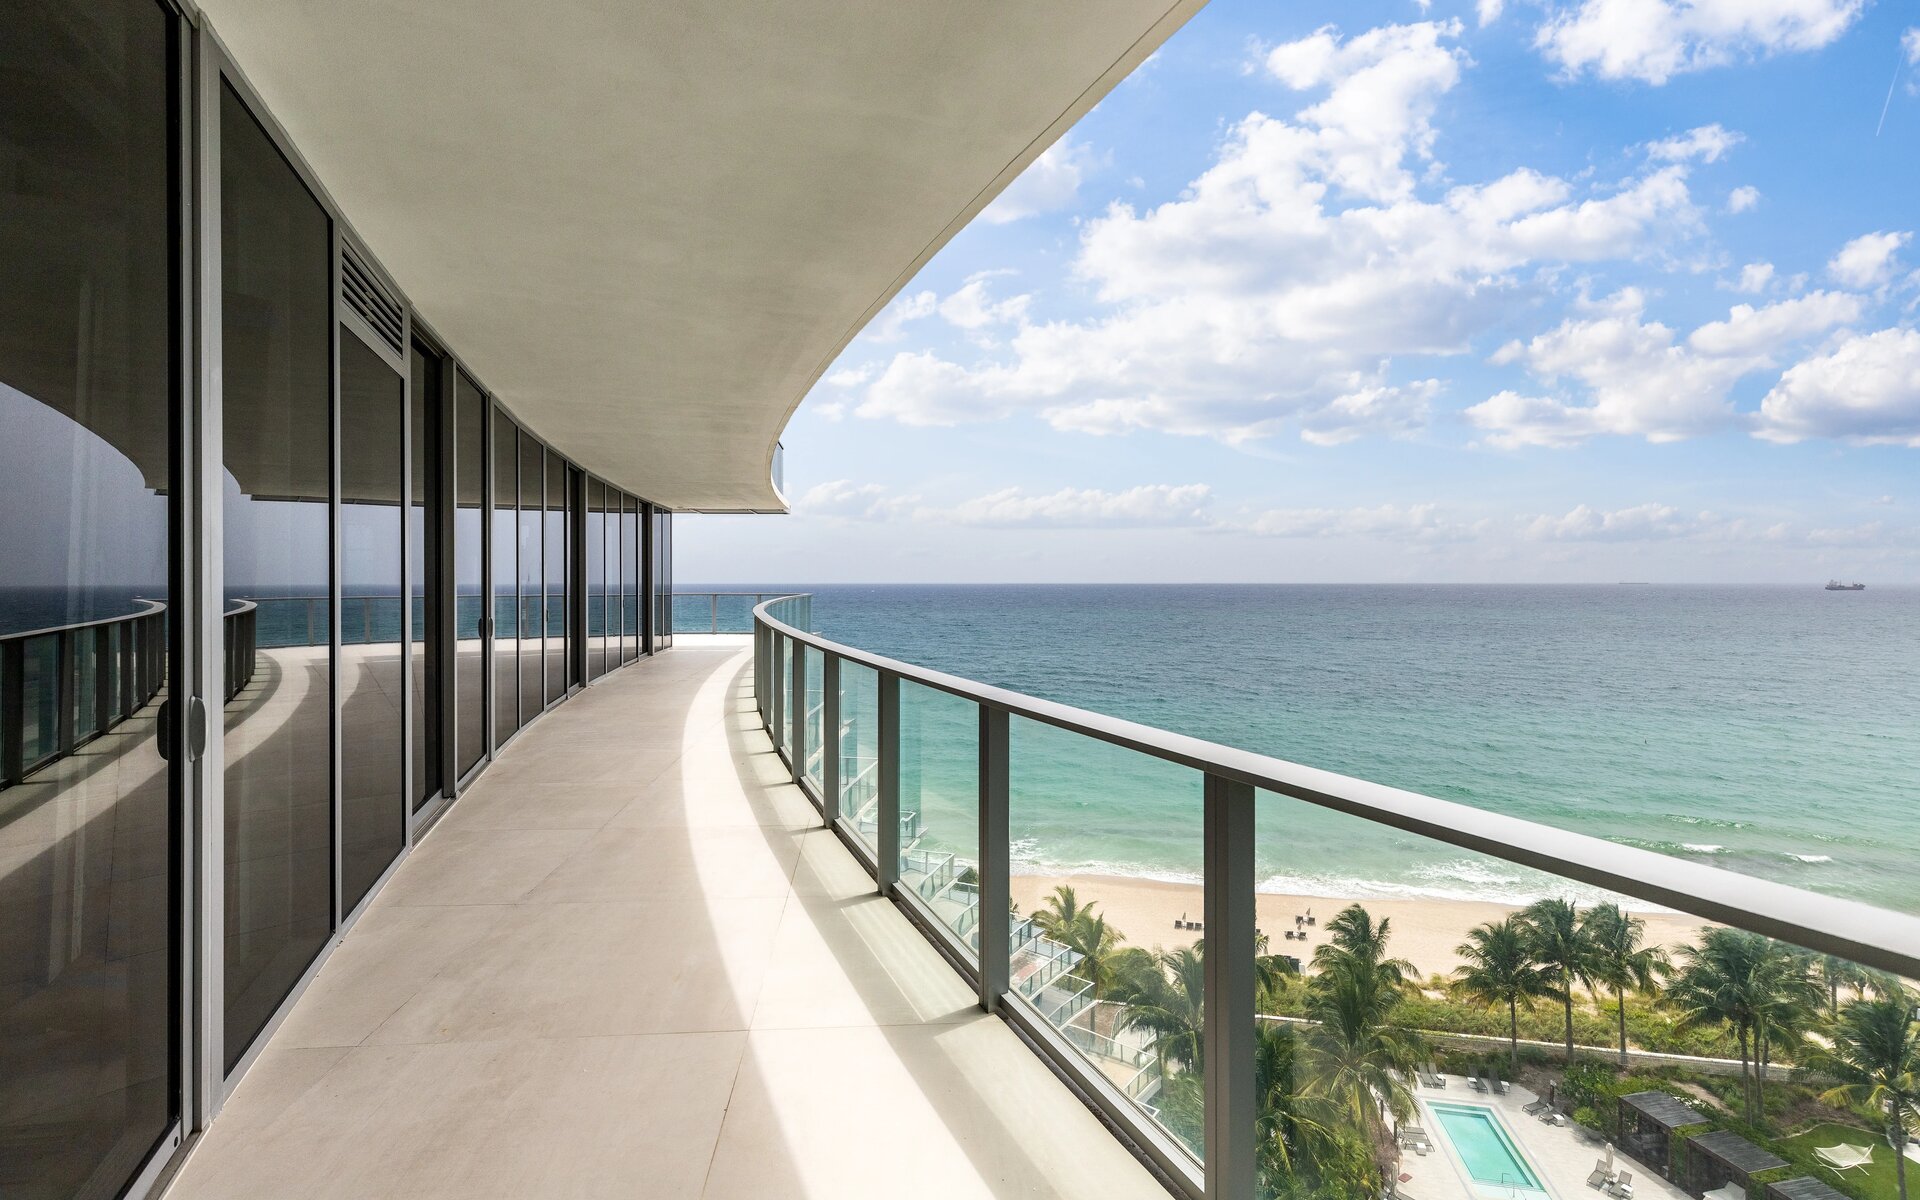
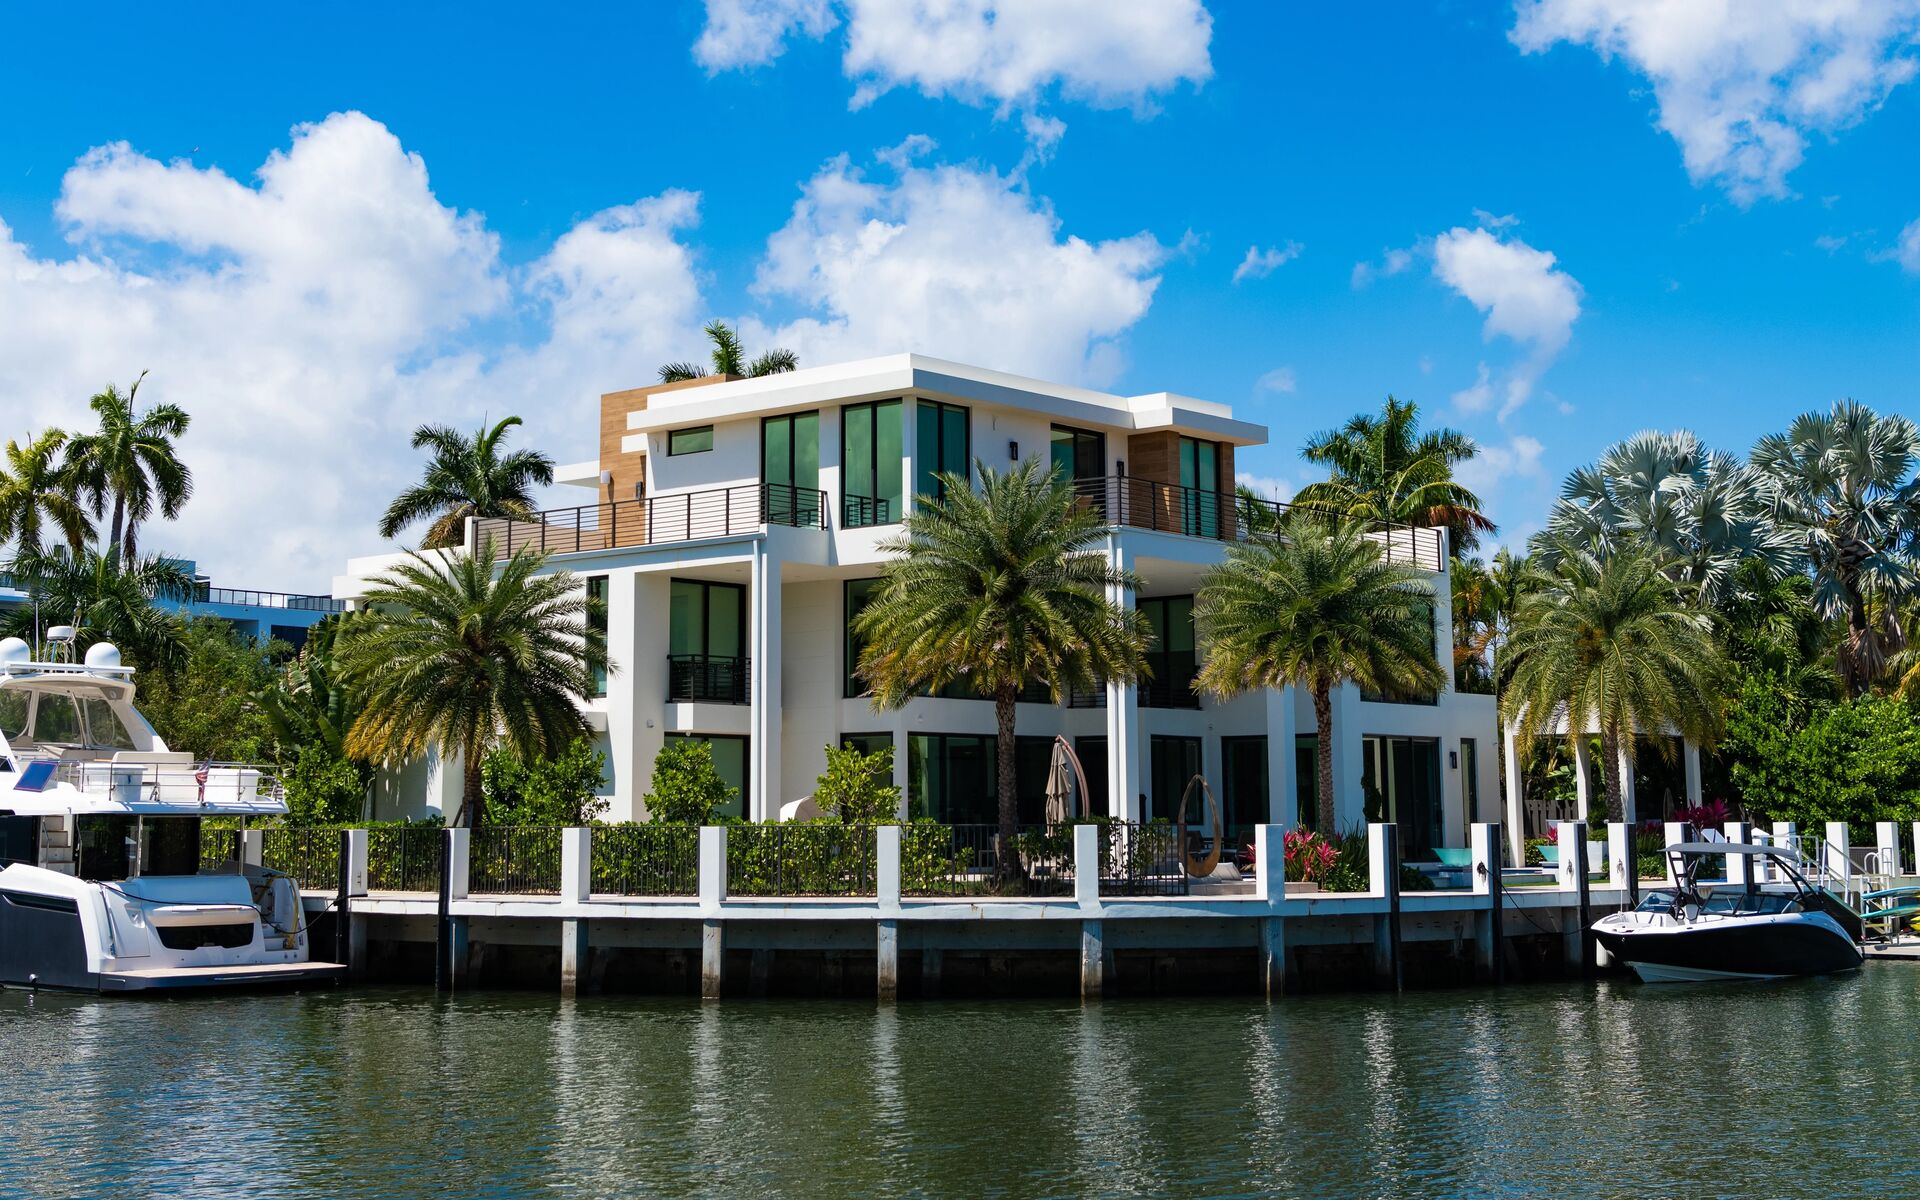
Beach condo terrace with ocean viewSingle-family waterfront home with pool and private dock

Luxury condo

Single-family waterfront

Control

The association decides budgets, repairs and rules

You decide, within city code

Monthly cost

HOA dues, which can include insurance, reserves and staff

Insurance, maintenance, seawall and dock upkeep paid by you

Biggest risk

Special assessments and reserve shortfalls

Seawall, roof, flood and storm exposure

Financing

The building must pass lender review

Lender reviews the house alone

Lifestyle

Lock-and-leave, staff, amenities

Privacy, outdoor space, a private dock

Boat

Slip availability varies; some buildings have none

Private dock, subject to canal and permit limits

For a condo, you're buying the building's balance sheet as much as the unit. Before you commit:

  • Milestone inspection. Condo buildings three or more habitable stories tall need one at 30 years, or 25 where the local agency requires it, and every 10 years after that. Fort Lauderdale's Building Safety Inspection Program starts at 25 years.
  • Structural integrity reserve study (SIRS). Most associations had to complete one by December 31, 2025. Buildings doing a milestone inspection in 2026 have until December 31, 2026.
  • Your cancellation window. For resale contracts signed on or after July 1, 2025, you can cancel within 7 days (excluding weekends and legal holidays) after you receive the association's documents (§718.503, F.S.). Use those days to read the budget, reserves, minutes and planned assessments.
  • Rental and pet rules are in the declaration. Read them before you assume.

Considering new construction? See Developments for the towers I follow, and read Las Olas condos vs. single-family homes: how to choose.

Chapter 6

What it costs to buy in Broward County

Closing costs in Florida follow local custom, and the contract decides. In Broward, the buyer customarily pays for the owner's title insurance and chooses the title agent, and the seller customarily pays the documentary stamp tax on the deed. Everything here is negotiable.

Example: a $5,000,000 purchase with a $3,500,000 loan

Item

How it's calculated

Example

Owner's title insurance

Florida's promulgated rate: $5.75 per $1,000 up to $100K; $5.00 per $1,000 up to $1M; $2.50 per $1,000 up to $5M; $2.25 per $1,000 up to $10M

$15,075

Lender's title policy

Issued with the owner's policy for a minimum $25, plus endorsements

$25 and up

Doc stamps on the mortgage

$0.35 per $100 of the loan

$12,250

Intangible tax on the mortgage

0.2% of the loan

$7,000

Recording fees

$10 for the first page, $8.50 for each additional page

Varies

Inspections

General, wind mitigation, marine/seawall, survey, plus pool and dock as needed

Quote for each home

Lender costs

Appraisal, origination and prepaid interest

Lender-specific

Prepaids

First-year insurance premiums, plus a tax escrow if you're financing

Varies

Title agents add search, exam and closing fees on top of the premium. Get a written estimate from your title agent and lender.

Plan for the property-tax reset. The seller's capped assessment doesn't transfer to you; the home is reassessed at market value the next January 1. Fort Lauderdale's 2025 total millage was about 18.45 mills ($18.45 per $1,000 of taxable value) in the main city district. A home assessed at $4,500,000 without homestead would owe about $83,000 a year. The Property Appraiser sets the assessed value, which often differs from your price.

Buying in Sunny Isles Beach or Golden Beach? Miami-Dade's deed stamp rate is $0.60 per $100, plus a $0.45 surtax on transfers other than single-family homes, and local customs differ.

Your buyer's agent's compensation is negotiable and set in a written agreement that you sign before touring homes. That has been the national practice since August 17, 2024.
Chapter 7

Relocating to Fort Lauderdale

Homestead and Save Our Homes

If this will be your primary residence, Florida's homestead exemption is the biggest tax lever you have.

  • Qualify: own and live in the home as your permanent residence on January 1, then file with the Broward County Property Appraiser by March 1.
  • Amount: up to $51,411 off assessed value in 2026.
  • Save Our Homes caps annual assessment increases at 3% or CPI, whichever is lower.
  • Portability: you can carry up to $500,000 of an existing Florida homestead's benefit to a new one, within three years.
Amendment 3 on the November 3, 2026 ballot

Voters decide Amendment 3 on November 3, 2026 (60% needed). If it passes, the non-school homestead exemption rises to up to $150,000 in 2027 and $250,000 in 2028. Per the ballot summary, people who are not Florida residents on December 31, 2026 would start with the existing exemption and get the larger one in their fifth year. If you're planning a move, ask your CPA or attorney about timing now.

Glen Primak on Las Olas Boulevard in Fort Lauderdale

Domicile in practice

Florida has no state personal income tax. Moving your domicile usually means recording a Declaration of Domicile with Broward County ($10), getting a Florida driver's license within 30 days of becoming a resident, registering to vote, and moving your banking and daily life here. Your former state may audit the move, so use a CPA who has handled it before.

Buying from out of town

I preview homes and docks by video and hand you a shortlist before you fly in. Then we tour by car and by water. One referring agent wrote that I "personally picked them up from the airport" for an international client (testimonials).

Chapter 8

Off-market and pre-market access through SERHANT.

Some of the best homes trade quietly. Sellers can choose a delayed-marketing listing (in the MLS for agents, held off public sites for a period) or an office-exclusive listing (not publicly marketed). Either way, well-connected agents see them first.

SERHANT. operates in 20 markets with nearly 2,500 agents (company figures, October 2026). That network brings pre-market homes and serious sellers that never reach a portal. To get access:

  • Share your criteria privately: neighborhoods, budget, vessel and timeline.
  • Have proof of funds or a lender pre-approval ready. Sellers of private listings ask for it before any showing.
  • I'll call you when something fits, often before it's public.

You can also browse my exclusive properties and past transactions.

Get on the private list

Off-market and coming-soon homes from my SERHANT. network, matched to your criteria and shared privately.

Chapter 9

Your timeline, from first call to keys

Stage

What happens

Typical timing

Day 1

Consultation: goals, budget, Dock-Fit numbers, financing path

20–45 minutes

Days 2–3

Curated shortlist with my notes on water, wall, flood and building

Within 48 hours

Week 1–2

Private tours by land and by water

Your schedule

Offer

Strategy on price, terms, inspection period and contingencies

Same day as the decision

Inspection period

House, seawall, dock, wind mitigation, survey, insurance quotes, condo documents

As negotiated in the contract

Financing and insurance

Appraisal, loan approval, policies bound

Lender-specific

Closing

Title, final walk-through, wire, keys

Often 30–45 days financed, faster with cash

Timing matters on the calendar too. The Fort Lauderdale International Boat Show (October 28–November 1, 2026) and the winter season bring more buyers to town. Hurricane season runs June 1 to November 30, and storms can pause insurance binding.

Glen Primak Delray Beach, FL Real Estate Agent Headshot

Glen Primak

Luxury Advisor

Chapter 10

Why buyers work with Glen

I'm Glen Primak, a luxury agent with SERHANT. in Fort Lauderdale, focused on waterfront homes and condos from Las Olas to Coral Ridge and the beach. I run these streets and tour these canals, so I know the market at street level and at water level. My job is honest advice, including when a home isn't the right one.

Words from clients

Glen Primak did an outstanding job selling my home in Hollywood, Florida. After two unsuccessful attempts with other agents, Glen came in with a clear, aggressive marketing plan and actually executed on it. From day one he was proactive, strategic, and completely transparent throughout the entire process. What really stood out was his honesty and communication. In an industry where those qualities can so...

— Stephanie K.

I’m an agent in Maui and have known Glen through the Serhant network for a while. When one of my clients told me they were planning a full relocation to South Florida, I immediately thought of him. Moving across the country is a big step, and my clients were looking for someone who could really help them understand the different areas and find the right fit for their lifestyle. Glen spent time walking th...

— Linda

Glen Primak was incredible to work with. I was buying a condo at Riverhouse and didn’t know the area very well, but Glen took the time to explain everything and show me multiple options that made sense for what I was looking for. What impressed me the most was his negotiation. I still can’t believe the deal he was able to get done for us. He clearly knows the market and how to position things to his clie...

— Travis B.

I’m an agent based in Mallorca and have known Glen for some time through the Serhant network. When one of my clients mentioned they were interested in purchasing a property in South Florida, Glen was the first person that came to mind. Referrals are something I take very seriously, especially when they’re trusted clients, so it was important to me that they were in good hands. Glen did a fantastic job fr...

— Matt W.

As a mortgage broker in New York, I’m careful about who I refer clients to, especially in competitive luxury markets. Glen Primak was an easy choice. I recently sent a client his way because of his deep knowledge of Fort Lauderdale, particularly Las Olas and the waterfront luxury space. He understands the nuances of these neighborhoods, the lifestyle they offer, and how to guide clients at a high level. ...

— Uran B.

Working with Glen was an excellent experience. He helped me find a niche waterfront property off Las Olas in Fort Lauderdale that would have been very difficult to identify without his local knowledge and connections. Glen was professional, responsive, and genuinely invested in making sure I found the right property rather than just closing a deal. His guidance throughout the process made everything smoo...

— Benjamin K.

Seriously, the best realtor I have ever worked with in my life. Explained everything clearly. Extremely responsive. Negotiated hard for everything that I wanted. Never felt pressured to make a decision. I cannot recommend Glen highly enough. Outstanding Realtor.

— Donny Z.

I’m always careful about who I refer my clients to—especially when they’re traveling internationally to look at property. When one of my clients mentioned they were planning a trip to South Florida, I connected them with Glen Primak at Serhant Florida. From the moment they arrived, Glen really went above and beyond. He personally picked them up from the airport, spent time showing them different neighbor...

— Peter B.

I recently referred clients to Glen that were moving from Denver to South Florida. Knowing that Glen is the go-to Realtor for this area, I knew they would be in great hands. They are thrilled to have purchased a luxury waterfront home in the Los Olas area with his guidance. Glen made sure the transaction was seamless; he was extremely communicative and had their best interest the entire time. He’s even b...

— Maritt B.

Glen Primak made the entire process effortless. He was knowledgeable, responsive, and always had my best interests in mind. I got a great result and couldn't recommend him more!

— Sarah

Your next step

Buyer consultation
Private search
Free PDF

Download the Private Edition

The full guide, plus the Dock-Fit worksheet and a pre-offer due-diligence checklist.

Sending...
Successfully sent!
eBook Image
Frequently asked

Frequently asked questions

In Broward, buyers customarily pay for the owner's title insurance, which is set by state rates (about $15,075 on a $5 million purchase). Financed buyers also pay mortgage doc stamps of $0.35 per $100, a 0.2% intangible tax, recording fees, and lender and inspection costs. Sellers customarily pay the deed doc stamps. The contract decides.

The deed doc stamp tax is $0.70 per $100 of the price in every Florida county except Miami-Dade. That's $35,000 on a $5 million sale, and in Broward the seller customarily pays it. Mortgages carry a separate $0.35 per $100 doc stamp tax plus a 0.2% intangible tax, which the borrower pays.

It means every bridge between the dock and the ocean is a drawbridge that opens, so a tall boat can always get out. You may still wait for scheduled openings. Closed clearances on the Intracoastal are 25 feet at Sunrise Boulevard, 31 feet at Las Olas Boulevard and 55 feet at the 17th Street Causeway.

Yes. A general home inspection doesn't evaluate seawalls. Hire a licensed marine contractor or engineer. In Fort Lauderdale, a new or substantially repaired seawall must meet a 5.0-foot NAVD88 elevation, or 4.0 feet if permitted before 2035 and designed to reach 5.0 feet by 2050. A large repair can turn into a full rebuild.

Lenders require it in high-risk flood zones (AE and VE). Starting January 1, 2027, Citizens requires flood coverage on every residential policy that includes wind, in any zone. NFIP policies cap building coverage at $250,000, so luxury homes usually add private excess flood. Get quotes before you make an offer.

For 2026, it's any loan above $832,750 for a single-family home in Broward County. Jumbo lenders set their own down payment, cash reserve and debt-to-income rules. Many $2M+ buyers also use portfolio or asset-based loans, or pay cash.

Pick a condo if you want lock-and-leave living, staff and amenities, and you're comfortable reviewing the building's reserves, inspections and assessments. Pick a single-family home for privacy, outdoor space and a private dock, and budget for insurance, the seawall and maintenance.

Check the milestone inspection report, the structural integrity reserve study, the current budget and reserve funding, board minutes, and any planned special assessments. Resale buyers have 7 days (excluding weekends and holidays) after receiving the association's documents to cancel. Lenders now review the building's finances too.

Own the home and live in it as your permanent residence on January 1, then file with the Broward County Property Appraiser by March 1. The 2026 exemption is up to $51,411, and Save Our Homes caps future increases in your assessed value at 3% or CPI, whichever is lower.

Yes. Some sellers choose delayed-marketing or office-exclusive listings that don't appear on public sites. Working with an agent connected to a large network, such as SERHANT., and sharing your criteria and proof of funds in advance is the most reliable way to hear about them first.

Work With Glen

I provide discreet, strategic guidance in South Florida’s luxury waterfront market. With $200M+ in sales and strong property listings, I deliver exclusive opportunities and seamless transactions.